How to Read Your Credit Report for the First Time (Without Panicking)
KSKim Starks · July 29, 2026 · 4 min read
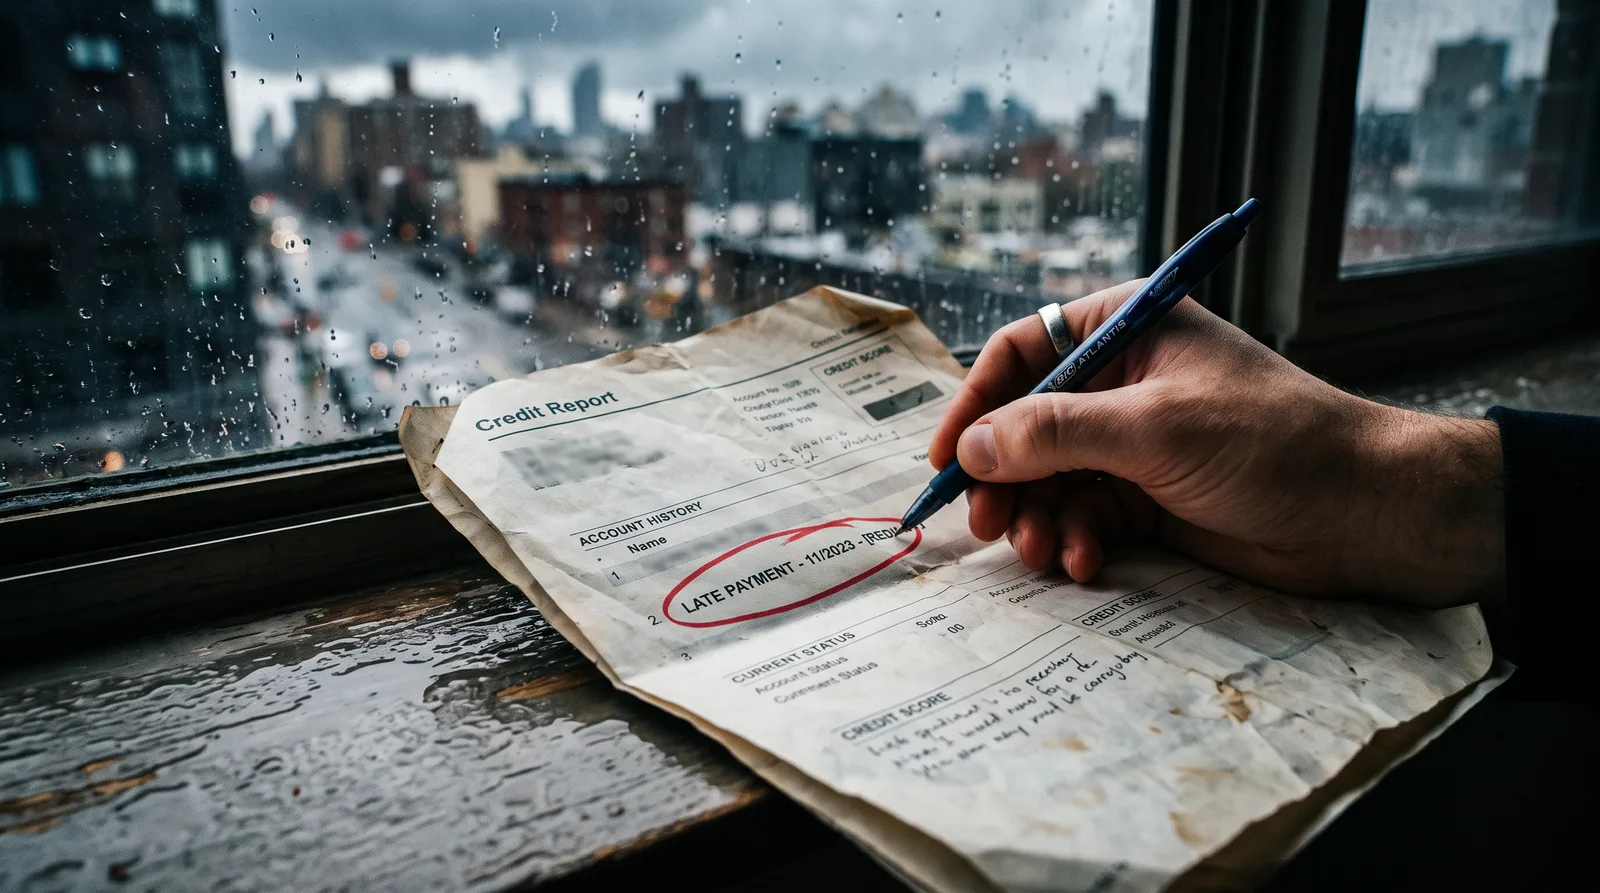
Pulling your credit report for the first time can feel like opening a letter you've been avoiding for months. The format is dense, the language is cold, and the numbers seem to carry a lot of judgment. I want to change that experience for you today.
Your credit report is not a verdict. It's a document — and like any document, once you know how it's organized, it stops being scary and starts being useful. Let's walk through it together, section by section.
Where to Get Your Report (The Only Official Source)
Go to AnnualCreditReport.com. That's the federally mandated, free site where you can pull reports from all three major bureaus: Equifax, Experian, and TransUnion. You don't need to enter a credit card. You don't need to sign up for a subscription. If any site asks you for payment to see your report, you're in the wrong place.
Pull all three reports, because they don't always match. Lenders report to bureaus differently, and errors on one report may not show up on another.
Section 1: Personal Information
The first section lists your name, current and previous addresses, date of birth, Social Security number (partially masked), and sometimes your employers. This section does not affect your credit score — but you should still read it carefully.
Why? Because errors here can be a sign of mixed files (your information accidentally merged with someone else's) or identity theft. If you see an address you've never lived at or a name variation you don't recognize, flag it.
Section 2: Account History (The Heart of the Report)
This is the biggest section, and it's where most people freeze. You'll see a list of every credit account you've ever opened — credit cards, auto loans, student loans, personal loans, mortgages, and sometimes even medical collections.
For each account, look for:
- Account type — Is it a revolving account (like a credit card) or an installment loan (like a car note)?
- Date opened — Older accounts generally help your score; they show a longer credit history.
- Credit limit or loan amount — This anchors your credit utilization calculation.
- Current balance — What you currently owe.
- Payment history — This is the most important factor in your score. Look for any late payment markers, usually shown as 30, 60, or 90+ days late.
- Account status — Open, closed, paid, charged off, or in collections.
Don't panic if you see a closed account with late payments. Those marks have a shelf life. Most negative items fall off after seven years from the date of the original delinquency.
Section 3: Public Records
Not every report will have this section. If yours does, it typically shows legal financial events like bankruptcies. A Chapter 7 bankruptcy can stay on your report for up to ten years; a Chapter 13 for seven. Seeing this listed doesn't mean you're stuck — it means you have a timeline and a starting point.
Section 4: Inquiries
Every time a lender pulls your credit, it's recorded here. There are two types:
- Hard inquiries — These happen when you apply for credit (a card, a car loan, a mortgage). They can temporarily dip your score by a few points and stay on your report for two years.
- Soft inquiries — These happen when you check your own credit or when a company pre-screens you for an offer. They do not affect your score.
If you see hard inquiries you don't recognize, that's worth investigating — it could indicate someone applied for credit in your name.
What to Do After You Read It
Once you've gone through every section, do three things:
- Make a list of any errors. Wrong account, wrong balance, account that isn't yours, late payment that was actually on time — all of these are disputable directly with the bureau that's reporting the error.
- Note your oldest account and your current balances. These two data points alone tell you a lot about where your score stands.
- Breathe. Whatever you see on that report, it can be worked with. Nothing on a credit report is permanent.
Reading your report is the first act of credit literacy — and credit literacy is the foundation of everything that comes next, from getting approved for an apartment to walking into a mortgage closing with confidence.
If you want to go deeper — past the reading and into the actual repair, dispute, and strategy work — that's exactly what I built Credit Correction School for. Plain language, real tools, zero guesswork. You've already done the hardest part: you looked.
Want to go deeper than a blog post?
Credit Correction School
A step-by-step premium school that teaches you exactly how to understand, repair, and strengthen your credit — so you can confidently walk into any lender's office mortgage-ready. Plain language, real tools, zero guesswork.
Start learning — $44.99/mo